A practical guide to choosing the option that best supports your finances, lifestyle, and long-term goals.

Utah’s housing choices vary by city, neighborhood, budget, and how long you expect to stay.
Should you rent or buy in Utah right now? It is one of the most common questions buyers ask, but there is no one-size-fits-all answer. Buying is not automatically the smarter move simply because homeownership can build equity. The right decision depends on your income, savings, debt, timeline, lifestyle, and how comfortable you would feel carrying the full cost of owning a home.
For some people, renting is the financially stronger choice today. For others, buying can create long-term stability and the opportunity to build equity over time. The goal should not be “buy at all costs.” The goal is building financial stability and choosing the housing option that supports your life instead of controlling it.
| A better question than “Is buying smarter?” is: “Which option keeps my finances healthy and supports my next few years?” |
When Renting May Be the Better Choice
Renting can be a smart strategic decision, especially when your life is still changing. The flexibility of a lease may be more valuable than owning a property if you are uncertain about where you will be living a year or two from now.
You may relocate soon for work, school, family, or lifestyle reasons.
You do not yet have a solid emergency fund.
Your income is variable, seasonal, or otherwise unstable.
The full cost of homeownership would leave you financially stretched.
Renting also shifts many major repair responsibilities to the landlord. If the water heater fails or a major system needs work, that expense is usually not coming directly out of your savings. For someone still building financial reserves, that predictability can be valuable.

Renting can provide flexibility while you strengthen savings, stabilize income, or clarify where you want to live long term.
The Hidden Costs of Homeownership
When people compare renting with buying, they sometimes compare rent only with the mortgage payment. That is not a complete comparison. Owning a home comes with additional expenses that can materially change the monthly budget.
Repairs and ongoing maintenance, from appliances to plumbing, HVAC, roofing, and exterior upkeep.
Property taxes, which can change over time.
Homeowners insurance and possible increases in premiums.
HOA fees when the property is part of an association.
Unexpected emergencies that require cash quickly.
A home can still be affordable with these expenses, but they need to be included before you make the decision. If buying would require you to drain your savings or rely on credit cards when something breaks, waiting may be the healthier financial choice.
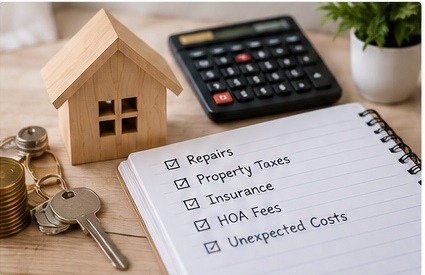
The real cost of ownership includes much more than the mortgage payment.
When Buying a Home Can Make Sense
Buying may make more sense when you have stable income, emergency savings, and a realistic plan to stay in the area for several years. A longer time horizon gives homeownership more room to work because buying and selling both involve transaction costs, while short-term market movements are difficult to predict.
Mortgage payments can help you build equity over time.
A fixed-rate mortgage can provide greater principal-and-interest payment stability than renewing a lease each year.
You have more freedom to improve and personalize your space.
Long-term ownership may provide appreciation, although home values are never guaranteed to rise.
The strongest reason to buy is not fear that prices will run away or pressure to become a homeowner. It is that the home fits your budget, your plans, and your lifestyle. A purchase that still leaves room for savings, emergencies, travel, investing, and everyday life is usually much more sustainable.

Buying can support long-term stability when the payment and ongoing ownership costs fit comfortably within your budget.
Rent vs. Buy Is a Local Utah Decision
The answer can also change based on where you want to live. Salt Lake City, South Jordan, Sandy, Draper, Lehi, Orem, Provo, Saratoga Springs, Layton, Ogden, and surrounding Utah communities all have different home prices, rents, property types, and HOA structures.
That means a useful rent-vs-buy comparison should be based on the actual neighborhood and property type you are considering. A condo or townhome may create a very different ownership budget than a detached house, and rent levels can vary significantly even between nearby communities.
Five Questions to Ask Before You Decide
| 1. How long do I realistically expect to stay?If you may move soon, renting can protect your flexibility and avoid the cost and hassle of selling shortly after buying. |
| 2. Will I still have emergency savings after closing?Owning is safer when an unexpected repair does not immediately push you into new debt. |
| 3. Is my income stable?A consistent income makes mortgage payments and ownership expenses easier to manage. |
| 4. Does the full ownership cost fit comfortably?Compare rent with the mortgage plus taxes, insurance, maintenance, HOA fees, and reserves. |
| 5. Am I buying because it fits my goals or because I feel pressure?Homeownership should strengthen your long-term plan, not make your monthly life harder. |
Frequently Asked Questions
| Is buying always better than renting in Utah?No. Renting may be the better choice when you need flexibility, lack emergency savings, have unstable income, or would be financially stretched by ownership. |
| How long should I plan to stay before buying?There is no exact rule for everyone, but buying generally becomes more practical when you expect to stay long enough for the costs and responsibilities of ownership to fit your plans. |
| What ownership expenses do buyers often underestimate?Repairs, maintenance, property taxes, homeowners insurance, HOA fees, and unexpected emergencies are easy to overlook. |
| Can renting be part of a good long-term financial plan?Yes. Renting can give you time to increase savings, reduce debt, stabilize income, or wait until your location and long-term goals are clearer. |
Final Thoughts: Choose Stability, Not Pressure
If you may relocate soon, do not have emergency savings, have unstable income, or would feel stretched by the full cost of ownership, renting may be the smarter choice right now. If your finances are stable and you expect to stay for several years, buying can help build equity and create greater housing stability.
There is no prize for buying before you are ready. The best housing decision is the one that protects your finances today while supporting the future you actually want.
| Trying to decide whether buying in Utah makes sense for you?Rylee Harris can help you compare Utah communities and understand the home-buying side of the decision without pressuring you to buy before the numbers make sense.Phone: +1 (208) 530-5271 | Email: ryleeharris@kw.comContact Rylee at Visionary Living Realty |